Filing Modelo 303 with only foreign clients: why the IVA is zero and you still file
You still file. An autónomo registered in régimen general with quarterly returns submits a Modelo 303 every quarter, even when the result is zero (RIVA art. 71). Services to businesses outside Spain are not supplied in Spain (LIVA art. 69), so no Spanish IVA is charged: EU clients with a valid VAT number go in box [59], clients outside the EU in [120]. In a real Q3 2026 return, 9,993.00 € and 3,576.24 € gave a result of 0.00 €.
Why your foreign invoices carry no Spanish IVA
IVA is Spain's VAT, and it follows the place where a service is supplied, not the place where the freelancer lives. When the client is a business acting as such and its seat is outside the Spanish IVA territory, the service is treated as supplied where the client is (LIVA art. 69). No Spanish IVA goes on the invoice. Inside the EU, the client then accounts for the VAT in its own country under the reverse charge (Articles 44 and 196 of the EU VAT Directive 2006/112/EC). Outside the EU, any local tax is the client's business.
The rule has exceptions. LIVA art. 70 keeps some services in Spain whoever pays for them: work on a building located here, passenger transport, restaurant and catering services. A developer, translator, designer or consultant billing companies abroad is normally outside that list.
Zero IVA is not the same as no return. The Modelo 303 is the quarterly IVA self-assessment, filed online in the Sede, the AEAT's electronic office. An autónomo (a self-employed person) whose census record shows régimen general with quarterly returns files one every quarter, even with nothing charged and nothing to deduct (RIVA art. 71). People whose only activity is exempt, or retailers in recargo de equivalencia, are outside that obligation.
A real quarter: France, Hong Kong and the US, result 0.00 €
On 19 October 2026 an autónomo registered in régimen general since 1 July filed the Q3 2026 return. AYFI prepared the figures from the quarter's invoices; the holder filed it with their own certificate. One client was a company in France, the others were companies in Hong Kong and the United States. Total turnover 13,569.24 €, Spanish IVA charged 0.00 €.
| Client | Box | Real Q3 2026 return | Example in the screenshots |
|---|---|---|---|
| Company in France, valid EU VAT number | [59] | 9,993.00 € | 6,000.00 € |
| Companies in Hong Kong and the US | [120] | 3,576.24 € | 2,400.00 € |
| Total IVA charged | [27] | 0.00 € | 0.00 € |
| Total IVA to deduct | [45] | 0.00 € | 0.00 € |
Boxes [59] and [120] sit on the page «Información adicional» (additional information), not on the pages where the IVA charged is calculated. With no other sales, [27] stays at zero; with no expense invoices carrying IVA that quarter, so does [45].
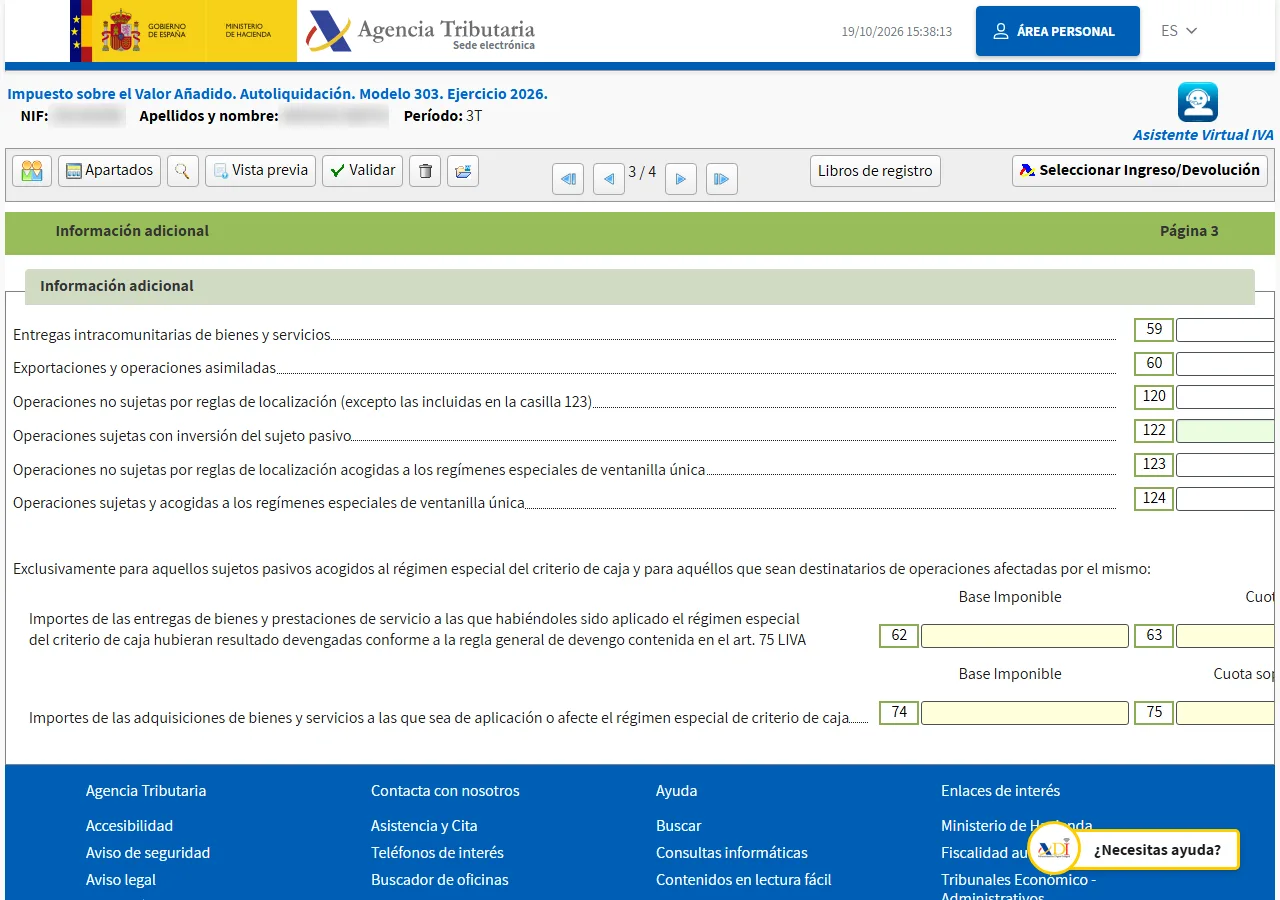
One point catches British readers: a client in the UK goes in [120], not [59]. Since 2021 the UK is outside the EU VAT area, so a London agency is treated like a New York one. Box [59] also needs the EU client's VAT number to be valid at the time of the service.
Timing follows the work, not the paperwork. A service counts in the quarter in which it is supplied (LIVA art. 75), not the quarter of the invoice or of the registration. That is why an invoice from June stayed out of this Q3 return.
Zero IVA charged does not cancel the right to deduct. IVA paid on business expenses is deductible when the service supplied abroad would give that right had it been supplied in Spain (LIVA art. 94), within the general rules of LIVA arts. 95 to 97. A consultant qualifies; someone supplying exempt services, such as healthcare, would not.
The zero return in the Sede, screen by screen
The Modelo 303 page on sede.agenciatributaria.gob.es lists several links for 2026. The one that files is «Presentación y servicio de ayuda Pre303». It asks for a certificado electrónico (digital certificate), Cl@ve or DNIe, then the year and the period: 3T for July to September.
Before the form comes the census window with the IAE activity code, the IVA regime and its start date. If those are wrong, the return is built on wrong data, and the fix is a Modelo 036, not anything inside the 303.
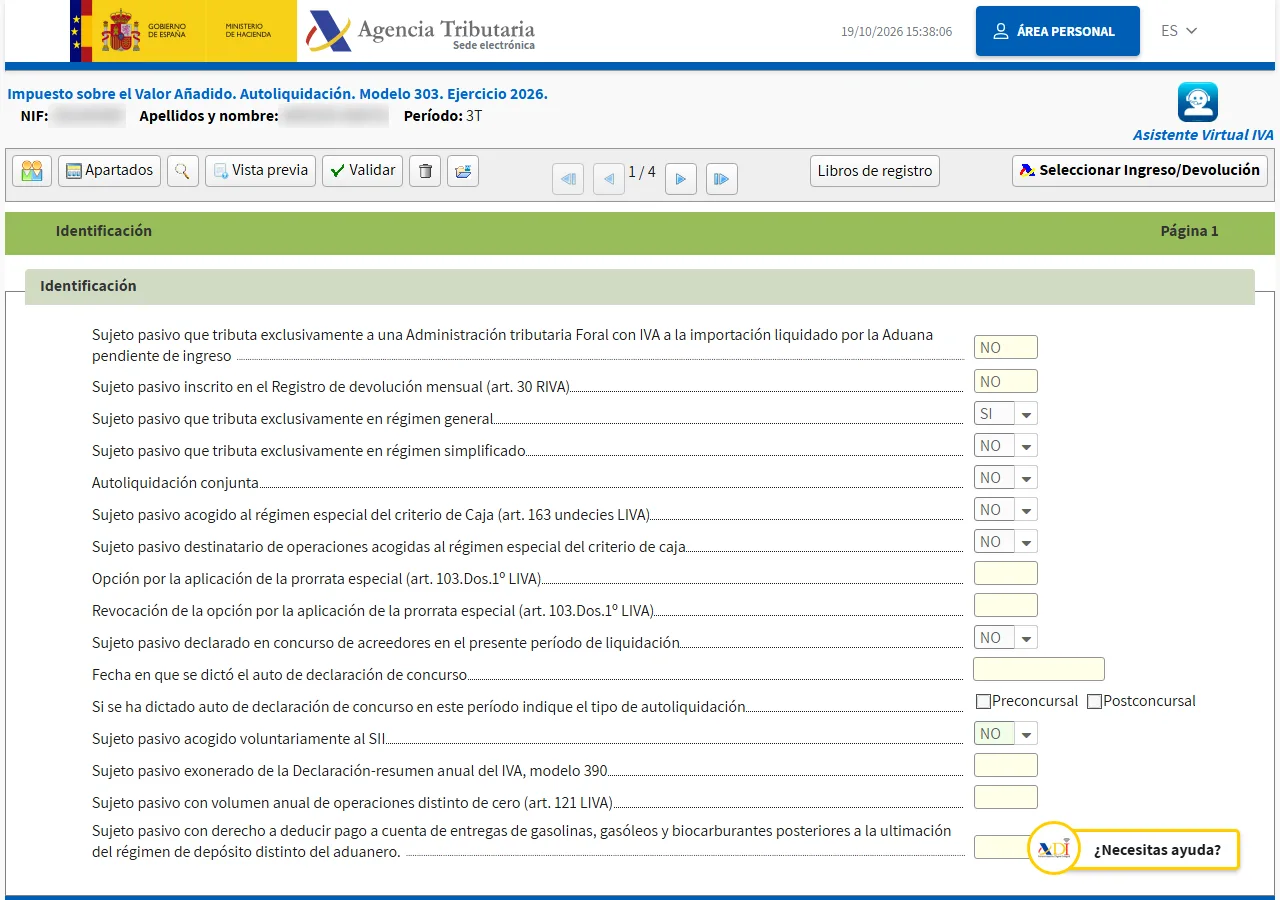
The page «Identificación» is a list of yes/no questions, most of them answered from the census. In the real return one stayed blank: whether the filer receives supplies under the cash-accounting scheme («criterio de caja»). On «Validar» the Sede answered with error PAR018, which means an unanswered question in «Identificación». The answer is «NO» unless a supplier invoices under that scheme, and its invoice would say so.
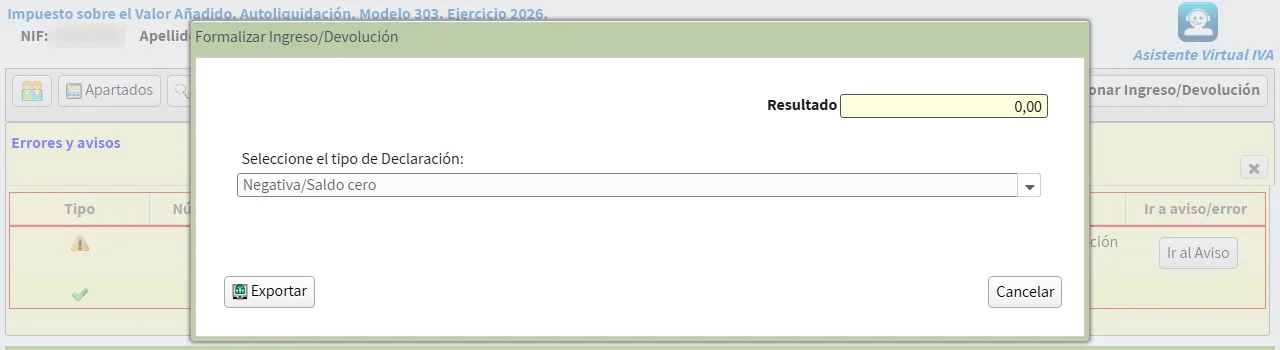
After validation the list showed «No existen errores» and warning 303M030: the filer is in régimen general and the return is empty. A warning does not block filing. «Presentar declaración» then opens «Formalizar Ingreso/Devolución», which picks «Negativa/Saldo cero» by itself and asks for no bank account. Tick «Conforme», then «Firmar y Enviar». The receipt reads «NEGATIVA/SIN ACTIVIDAD/RESULTADO CERO» and carries a number and a CSV (Código Seguro de Verificación) to download it again later.
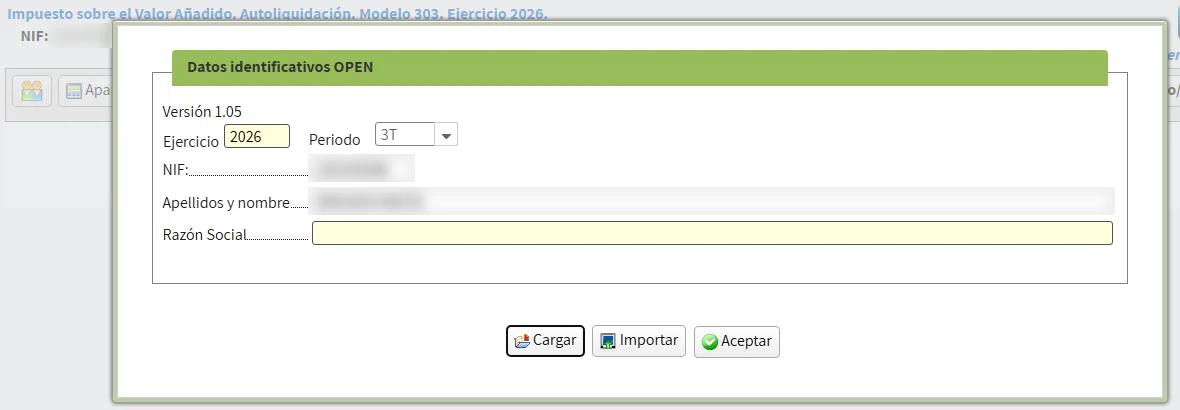
The screenshots come from the AEAT's «Simulador 303 (OPEN)», the same form without the sending step, filled with example figures rather than the real return.
If you are used to UK VAT returns or US sales tax
In the UK, a sole trader registers for VAT once taxable turnover passes the registration threshold, or chooses to register voluntarily. Below it there is no VAT on invoices and no VAT return, which is how many British freelancers have worked for years. Spain starts from the other end: the trigger is the IVA regime on your census record. Once you are in régimen general with quarterly returns, the 303 arrives every quarter, whether the turnover is large, small or entirely foreign.
The UK return is usually quarterly too, and filed through Making Tax Digital software. The Spanish one is typed into the Sede form, or imported from a file, and signed with your own certificate.
The United States has no VAT at all. Sales tax is a state and local tax, collected from the final buyer, and many states leave professional services outside it. A US freelancer selling only services often never registers for sales tax at all, and without a permit there is no return to file. Spain works the other way round: the return follows the registration, not the sales.
The reverse charge itself will feel familiar to anyone who has sold to EU businesses from the UK before 2021: the client, not you, accounts for the VAT. In Spain the invoice to an EU business client should say «inversión del sujeto pasivo» (reverse charge) and show the client's EU VAT number. Invoices in English are fine; the IVA treatment does not depend on the language of the invoice.
Deadline for Q3 2026: Tuesday 20 October
A quarterly 303 is due within the first twenty calendar days of the month after the quarter; the Q4 return runs until 30 January (RIVA art. 71). For Q3 2026 that means Tuesday 20 October 2026. AYFI prepares the boxes from the invoices issued and the expenses of the quarter; the filing, with your certificate, is yours.
Frequently asked questions
- What if my EU client is a private person, not a company?
- Then the general rule places the service in Spain and the invoice carries Spanish IVA (LIVA art. 69). Box [59] is only for business clients acting as such with a valid EU VAT number, which you can check on the European Commission's VIES service before invoicing.
- Is there another form for the EU client?
- Yes. Everything in box [59] is also reported client by client in the Modelo 349 for the same period, usually quarterly. Clients outside the EU, in box [120], need no 349.
- What happens if I skip a quarter because there is nothing to pay?
- The return is still overdue. LGT art. 198 treats a late return with no tax due as an infringement of its own, so a zero 303 filed late can bring a penalty even though the IVA was zero.
Sources
- AEAT — Modelo 303. IVA. Autoliquidación
- LIVA art. 69 — Place of supply of services
- RIVA art. 71 — Returns and filing periods
- Council Directive 2006/112/EC on the common system of VAT (arts. 44 and 196)
General information, not a substitute for a professional. AYFI files nothing for you.